If you’ve owned your home for a few years, you might be sitting on more equity than you realize. And if you need money for home improvements, debt consolidation, a major purchase, college expenses, or even your business, you don’t necessarily have to refinance your current mortgage to access it.
That’s where a Home Equity Line of Credit, or HELOC, can come in.
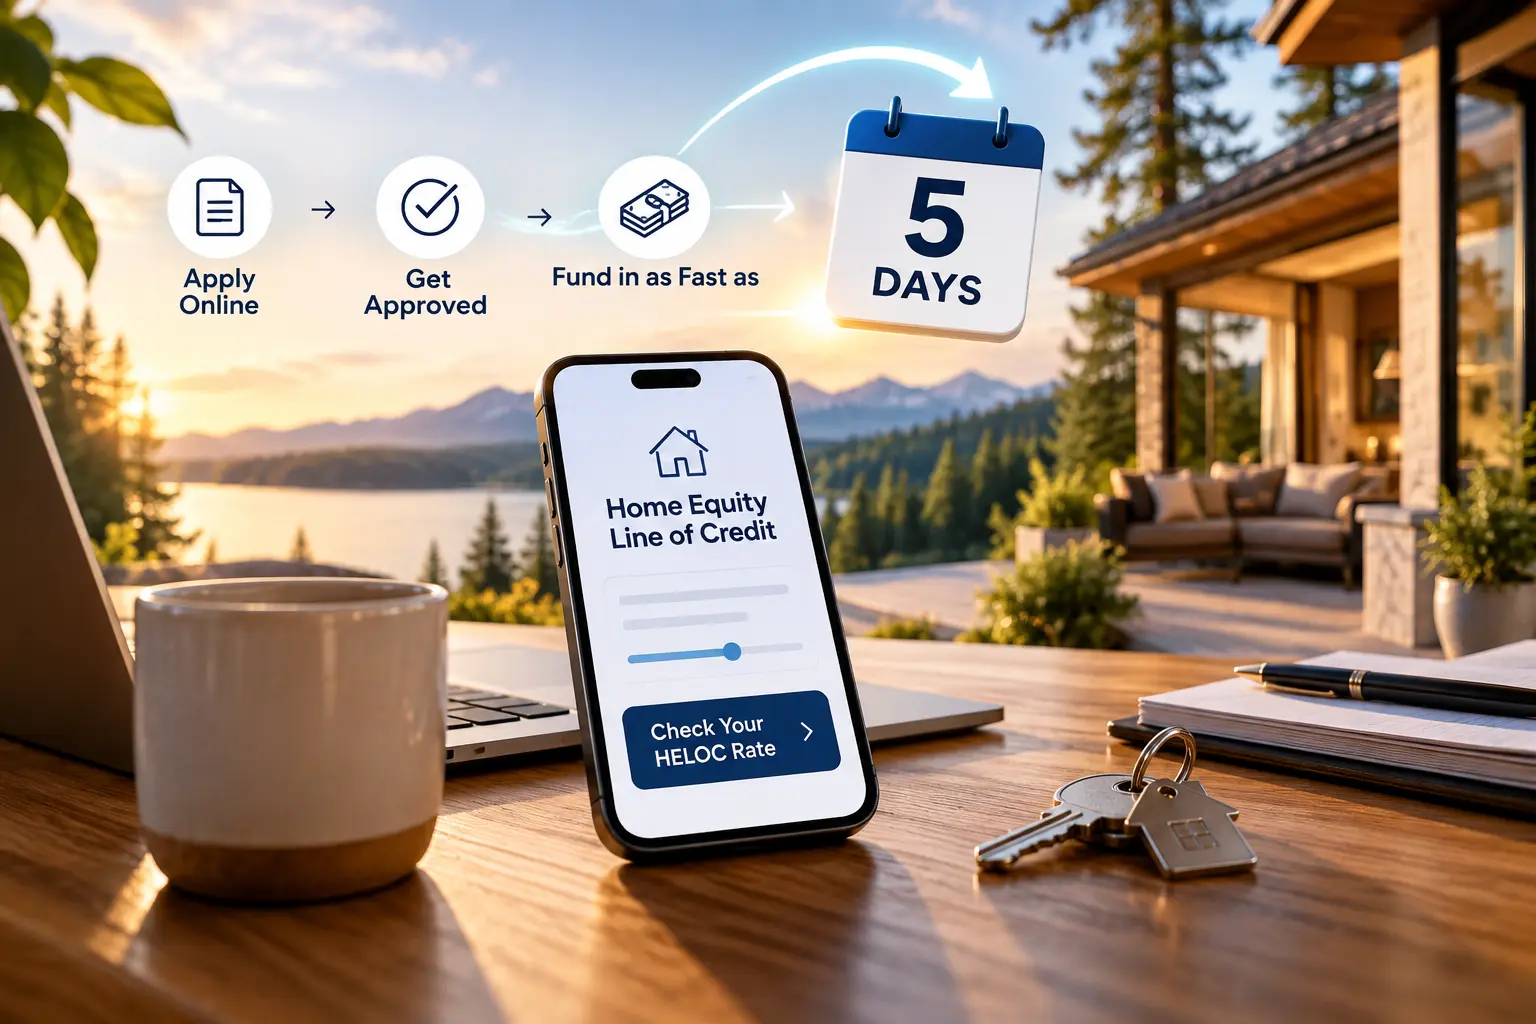
I’m excited to now offer a fully digital HELOC that makes accessing your home equity incredibly simple. You can check your rate online without impacting your credit score, complete the process digitally, and eligible homeowners may be able to receive funding in as few as five business days.
For homeowners here in Redding, throughout Northern California, and beyond, this can be a great option to explore when you need access to cash but want to leave your existing first mortgage alone.
What Is a HELOC and How Does It Work?
A HELOC allows you to borrow against a portion of the equity you’ve built in your home.
Your equity is essentially the difference between what your home is worth and what you still owe against it. How much you may actually be able to borrow depends on several factors, including your property value, existing mortgage balance and liens, credit profile, income, debt-to-income ratio, and the amount of equity available.
One of the biggest reasons I like having a HELOC as an option for my clients is that it generally doesn’t require you to refinance your existing first mortgage.
That matters.
If you already have a first mortgage you’re happy with, refinancing the entire loan just because you need access to some of your equity may not be the right move. A HELOC gives us another option to look at.
Our New Fully Digital HELOC Makes the Process Simple
This isn’t the old-school process of walking into a bank branch, filling out a stack of paperwork, and waiting weeks to find out what happens.
The application is 100% online.
You can start by checking your HELOC rate and potential terms with a soft credit pull, which does not impact your credit score. If you choose to continue with a full application, a hard credit inquiry will be required and may affect your credit.
For eligible borrowers, approval may be available in as little as five minutes, subject to verification requirements.
And eligible loans of $400,000 or less may be able to fund in as few as five business days when using remote online notarization and meeting applicable program requirements.
That combination of speed and simplicity is what makes this HELOC especially exciting.
You May Not Need an In-Person Appraisal
Here's another feature homeowners will appreciate.
For eligible HELOC amounts under $400,000, an in-person appraisal may not be required.
Property values can often be determined using automated valuation technology and independent property data instead.
Loans over $400,000 require an appraisal, and certain properties or situations may still require additional valuation or verification. But for many homeowners, being able to potentially skip the traditional appraisal makes the process much easier.
How Much Home Equity Can You Access?
HELOC amounts are available from $25,000 up to $750,000, depending on eligibility.
The amount you personally qualify for will depend on things like your:
Home value
Current mortgage balance and other liens
Available equity
Credit profile
Income and debt-to-income ratio
Property and occupancy type
Requested loan amount
And you don't have to try to figure all of this out on your own.
You can start online and see what HELOC options may be available based on your situation.
Checking your initial rate uses a soft credit pull and will not impact your credit score.
What Can You Use a HELOC For?
This is where a HELOC can become a really useful financial tool because there isn't just one reason homeowners use them.
You might use your home equity to remodel a kitchen, replace a roof, consolidate higher-interest debt, pay education expenses, cover a major expense, or put money into your business.
Every homeowner's situation is different.
For example, someone who wants $50,000 for a remodel has a very different goal from someone looking to consolidate debt or access $200,000 of their equity for a major expense.
That's why I don't believe in looking at a HELOC in a vacuum. We should look at what you're trying to accomplish and compare the financing options available to you.
Should You Get a HELOC or Do a Cash-Out Refinance?
This is one of the first questions I would want to answer with you.
With a cash-out refinance, we replace your existing first mortgage with a new, larger mortgage and you receive a portion of the difference in cash.
A HELOC is separate financing secured by your home, which means you can generally leave your existing first mortgage in place.
For homeowners who already have a mortgage they don't want to replace, that distinction can be huge.
But a HELOC isn't automatically the better choice. Depending on your existing mortgage, how much equity you need, your goals, and the financing available, a cash-out refinance could still make sense.
The goal isn't to pick a product first.
It's to figure out what you're trying to accomplish and then determine which option fits.
Fixed-Rate and Variable-Rate HELOC Options Are Available
There are also both fixed-rate and variable-rate HELOC options available, depending on your eligibility and program availability.
The initial amount funded with a fixed-rate option is based on a fixed interest rate. With a variable-rate HELOC, the interest rate can change over time based on the applicable index, which means your payment may increase or decrease.
If you're unsure which structure makes sense, that's a conversation we can have together before you make a decision.
Northern California Homeowners May Have More Equity Than They Realize
If you've owned a home in Redding, Red Bluff, Shasta County, or elsewhere in Northern California for several years, it may be worth finding out how much equity you currently have available.
You don't have to know exactly what your home is worth before starting.
And you certainly don't have to commit to borrowing money just because you're curious.
You can simply check your rate and potential options online and then decide whether a HELOC makes sense for what you're trying to accomplish.
Ready to See What Your Home Equity Could Do?
Your home equity can be a powerful financial resource when it's used thoughtfully.
Whether you're planning a renovation, trying to simplify debt, preparing for a major expense, or just curious about how much equity you could access, our new fully digital HELOC makes it easy to take the first step.
You can check your HELOC rate online without impacting your credit score and see what options may be available to you.
Loan approval, terms, loan amount, funding timeline, appraisal requirements, and availability are subject to borrower and property eligibility, verification, applicable program requirements, and other conditions. A hard credit inquiry is required if you proceed with a full application.